Understanding Southeast Asia’s Digital Landscape, Calculus, and Agency
Southeast Asia’s digital landscape is a pixelated patchwork of partners. As geopolitical tensions threaten a decoupling that will ripple through all aspects of technology including the rule-making frameworks that underpin the functionality of technology (tech), the viability of Southeast Asia’s preference for interconnected and interoperable infrastructure may increasingly be tested. The region would do well to assert its growing agency in this tech space by carving out its own digital future.
Southeast Asia’s digitalization-for-development agenda has been driven by a buoyant trifecta of consumers, industry, and government. The region’s tech space – populated by domestic and foreign stakeholders constructing subsea cables, satellite navigation systems, data centers, and a growing number of Smart Cities – reflects “the age of digital interdependence.” It is also a cautionary glimpse into the possibilities and constraints of the region’s future amid a deepening rift between the United States and China.
A Multi-Player Digital Landscape
Although the digital divide within and across Southeast Asian countries remains a significant impediment for the region, there is a growing population of mobile-first consumers to support a burgeoning “e-conomy.” Between 2020 and 2021, at the height of the pandemic and largely necessitated by lockdowns across different Southeast Asian cities and countries, 40 million additional people joined some 450 million of the region’s existing Internet users. The region’s digital economy is forecasted to exceed US0 billion by 2025, potentially hitting a value of US trillion by 2030.
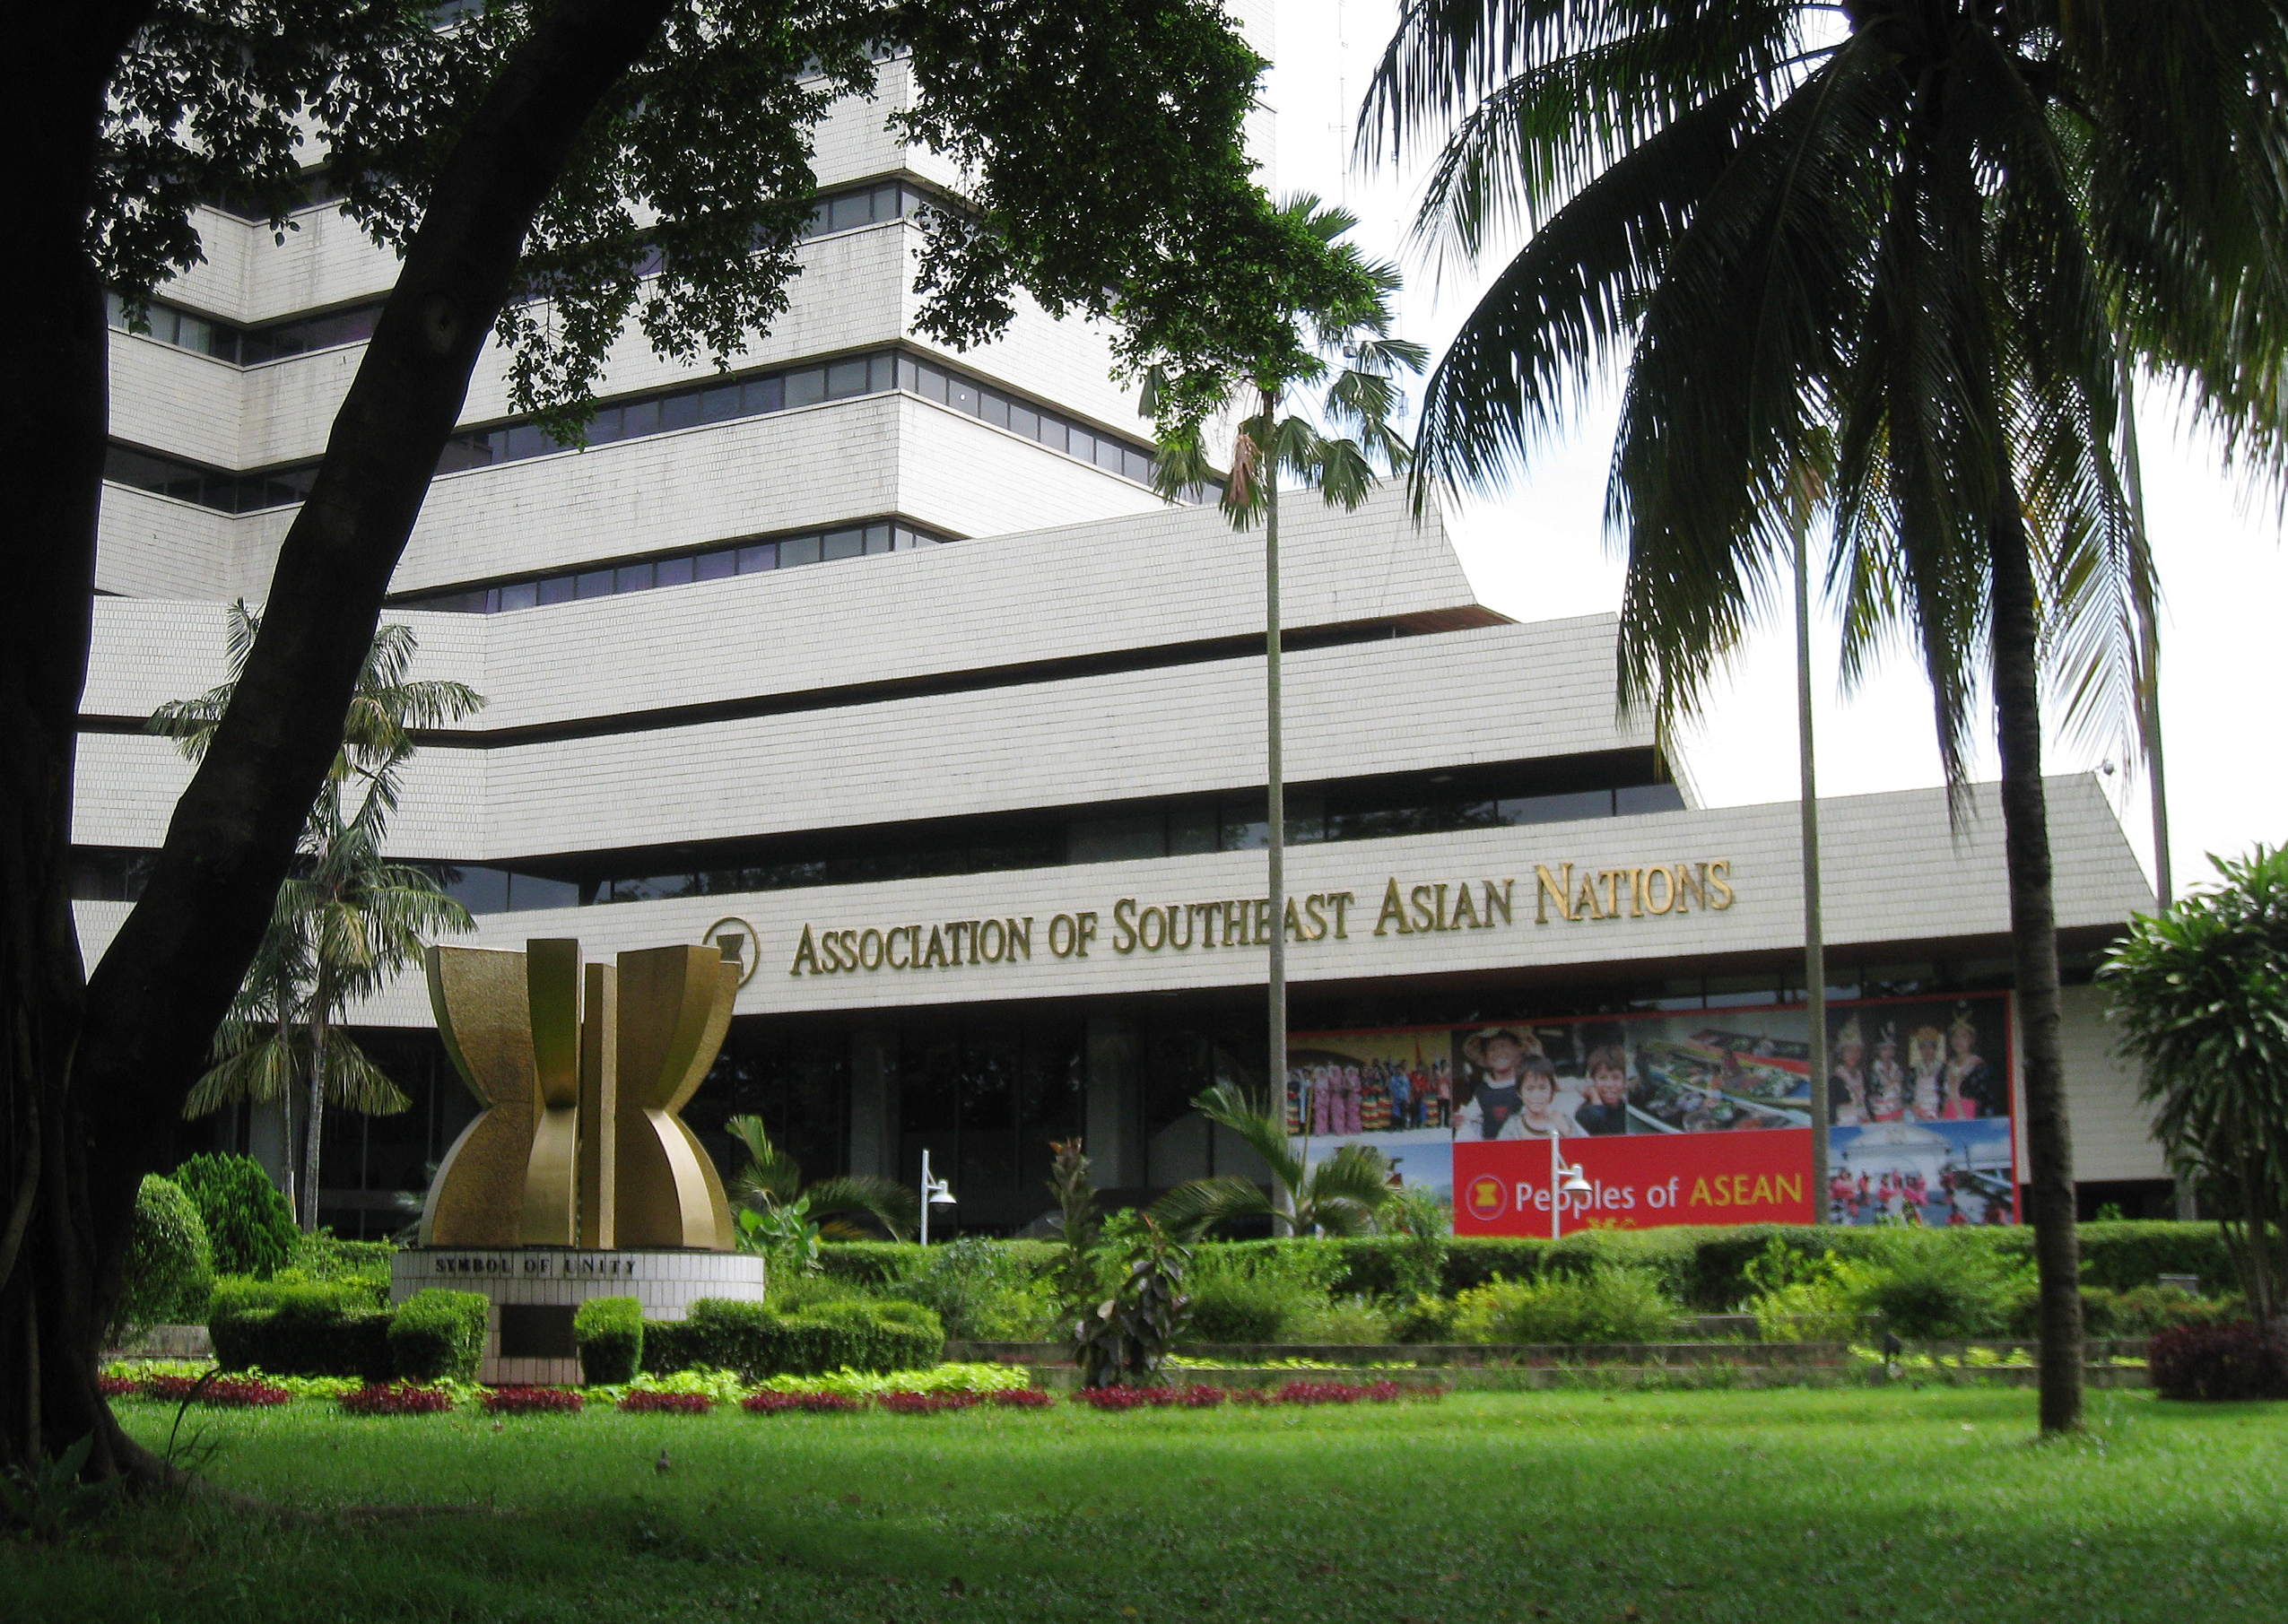
Investor confidence affirms this projection. Early American entrants such as Microsoft and Cisco that have long had a foothold in the Association of Southeast Asian Nations (ASEAN) region have been joined in recent years by Amazon Web Services, Google, and Meta. In addition to constructing a US billion data center in Singapore, Meta is laying down three trans-Pacific submarine cables scheduled to come online in 2023 and 2024. Two of those cables are co-owned by Google in partnership with telecommunication companies in Singapore, Indonesia, and the Philippines. These huge capital outlays not only signal long-term presence but also planned market expansion and by extension, increased influence and leverage in the region.
Chinese tech giants, relative newcomers to the Southeast Asian market, have made up for time and in a big way. Tencent and Alibaba were early supporters of e-commerce growth in the region, investing in now mega-platforms such as Shoppee and Lazada. With between 50 to more than 70 percent of Southeast Asia’s population underbanked, it is little surprise that mobile wallets have become ubiquitous with Alipay dominating the regional market and WeChat Pay hoping to compete.
Although Southeast Asia’s robust start-up scene is indicative of the region’s bullish outlook, the vast majority of its economy is anchored by more conventionally structured and funded micro, small, and medium enterprises (MSMEs) which comprise an average 97 percent of all enterprises. Bringing MSMEs and therefore, most of Southeast Asia’s business population, online in order to advance inclusive growth necessitates improved digital access and interconnections of networks nationally and regionally.
This requires a symbiotic public-private ecosystem anchored by a clear vision, governance frameworks, and industry commitment. The e-ASEAN Framework Agreement formulated over two decades ago was an early show of acumen in registering the “opportunities from ICT and electronic commerce” for the region’s population.
Today, there is a plethora of ASEAN-wide and national level policies, strategies, and blueprints. At the regional level, these include the Masterplan on ASEAN Connectivity 2025, ASEAN Consolidated Strategy on 4IR, and ASEAN Smart Cities Network. At the national level, Southeast Asian governments are betting on a digitalized future with integrated high-tech national plans such as Singapore’s Smart Nation initiative, Thailand 4.0, and Malaysia 5.0. Indonesia’s National Artificial Intelligence (AI) Strategy outlines the country’s AI development framework for the next two decades while the Philippines has its own National AI Roadmap.
The sheer scope of each of these nascent plans requires a multitude of players, each bringing their own comparative advantages to match the varied national and regional capacities of Southeast Asia. Countries will vary with their own risk assessments and decisions will be based on a combination of technical, commercial, and political calculations. Underlying these considerations is a proclivity to enmesh partners into an interoperable and integrated framework, in line with the region’s general aversion to choosing sides.
Southeast Asia’s numerous partners are evident in documents such as the eighteen-country EAS Leaders’ Statement on ASEAN Smart Cities; initiatives such as the US-ASEAN Smart Cities Partnership and the ASEAN-China Science, Technology, and Innovation Cooperation; as well as technical assistance efforts funded by Japanese and European agencies, among others.
Differing Risk Calculations
It is crucial to understand that the framing of strategic risk is dramatically different among countries in Southeast Asia than it is for the United States and its allies. China is not viewed as an adversary even if its growing muscularity in the security arena generates concern and anxiety. Rather, China is as much an important partner in Southeast Asia’s digital and development agendas as are other powers.
This is true even of the United States’ oldest treaty ally in Asia: Thailand. The country’s Eastern Economic Corridor smart city initiative is jointly funded by China and Japan. Although Bangkok has stated it will be mindful of security-related concerns in its 5G core network, there are already plans for Huawei to build three 5G city benchmarks to support the Asia-Pacific Economic Cooperation Summit to be hosted in Thailand in November 2022.
The US-China technological rivalry that will be reinforced through the Australia-United Kingdom-United States (AUKUS) and Quad arrangements will have ramifications for the interoperability of different platforms, systems, and networks in Southeast Asia. For the ASEAN region, the preference for intra-regional connectivity through multi-partner integration will prove tricky if its choices are narrowed down to the proverbial binary. In some instances, the either-or choice may not even be practical or make much sense.
A number of Southeast Asian countries are trialing the deployment of both Huawei’s 5G and Open Radio Access Network (O-RAN) in different locations, based on topography and rural/urban density. Although O-RAN is touted as a competitive alternative to Huawei’s proprietary 5G offerings, the distinction is not as reductive. Huawei may not be a member of the operator-led O-RAN Alliance, which oversees O-RAN’s technical work, but China Mobile is a founding member of the Alliance and co-chairs ten out of its fourteen working groups. If the pitch is for O-RAN to best Huawei and by extension, China, in the 5G game, the O-RAN Alliance proves the field is more complex than it seems. Further, the lesson of Nokia suspending its technical work in the Alliance last year out of US entity list compliance concerns only underscores the hazards of the politicization of technology for Southeast Asia, which is already averse to entrapment in major power rivalry.
The parable of 5G has implications for other technologies such as artificial intelligence (AI). Significantly, the battle for technological—and therefore, political, economic, and military—ascendancy is being fought in the domain of technical standards; principles; as well as norms and international law.
